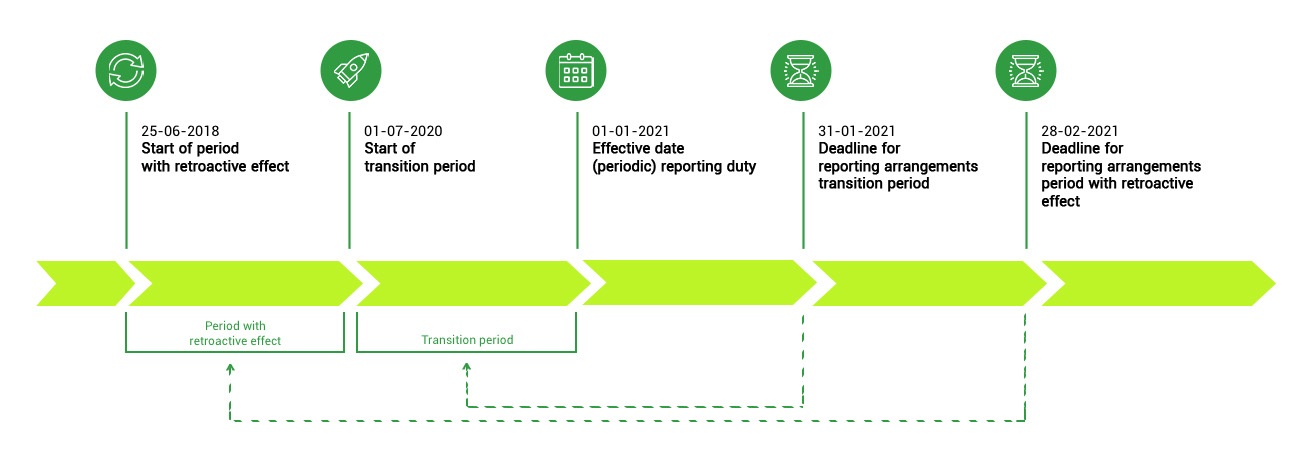
State Secretary Vijlbrief sent a letter to the Netherlands House of Representatives on 26 June 2020 in which he indicates that the Mandatory disclosure obligations will be deferred due to COVID-19. Reportable arrangements in the period 25 June 2018 to 30 June 2020 must be reported by the intermediary or relevant taxpayer no later than 28 February 2021. For additional background information concerning the Directive, please refer to our previous news article.
Furthermore, the announced guideline on reportable cross-border arrangements was published on 30 June 2020. This guideline concerns the Dutch implementation of Mandatory disclosure and contains illustrative examples.
When does the information have to be reported?
The deadline concerning the period 25 June 2018 – 30 June 2020 is not the only deferred deadline. The introduction of the reporting requirement with a deadline of one month has also been postponed. Until now, this reporting requirement would have taken effect on July 1, based on which the reports concerning the month of July would need to have been submitted no later than August 1. Reportable arrangements in the period 1 July 2020 – 31 December 2020 must be submitted no later than 31 January 2021 as a result of the deferral. The State Secretary has provided the following timeline:
Guideline reportable cross-border arrangements
The Guideline aims to provide a clarification of the legislation implementing Mandatory Disclosure. Examples are given of reportable arrangements and arrangements that do not need to be reported for each hallmark. We believe that the Guideline confirms that the Dutch implementation of the Directive particularly targets aggressive arrangements. The Guideline concludes that arrangements can be submitted to the Mandatory Disclosure Rules team of the Dutch Tax and Customs Administration in advance in an anonymous form to learn whether or not they must be reported in their opinion.
Risks
Baker Tilly has set up an internal management reporting system used to identify the risks and to meet the potential reporting duty. If we intend to submit a report, we will communicate this with the clients in question in advance. If you have any questions concerning Mandatory Disclosure, you can contact one of the members of the Baker Tilly MDD Team at [email protected].
This content was published more than six months ago. Because legislation and regulation is constantly evolving, we recommend that you contact your Baker Tilly consultant to find out whether this information is still current and has consequences (or offers opportunities) for your situation. Your consultant will be happy to discuss the latest state of affairs with you.
Other insights
-
Insight
Minimum taxation Pillar 2: exclusions, safe harbours, and pitfalls
The introduction of Pillar Two model in 2024 provides for a global minimum taxation for multinational enterprises and large companies. What are the exceptions and safe harbours may apply, and what are some of the pitfalls you must watch out for? Our experts explain all.
-
Insight
Pillar Two: How to prepare for the new minimum taxation
From 2024 onwards, multinational enterprises and large companies may be required to pay top-up tax under the Minimum Taxation Act 2024. How do you ensure that your company is properly prepared? We will describe the required steps below.
-
Insight
Pillar Two: Introducing a minimum level of taxation for multinational enterprises and large companies in 2024
On 1 January 2024, a new set of rules for charging taxes will be introduced for multinational enterprises and large companies. What does this minimum tax involve, and what additional taxation and requirements should you expect?